If you are sourcing g657a2 bare fiber for FPV drone tethers or specialty sm fiber assemblies today, you have likely encountered a frustrating reality: quotations are valid for days, not weeks; suppliers ask for deposits before confirming capacity; and delivery schedules stretch into 2027. This is not a temporary hiccup. It is the result of a structural collision between explosive new demand and a supply chain that physically cannot respond fast enough.
This article breaks down the root causes behind the G657A2 shortage in China, examines verified price data, and offers actionable procurement advice for buyers of drone fiber optic and related specialty fibers.
The Demand Shock: Two Unlikely Forces Collide
AI Data Centers Are Consuming Fiber at an Unprecedented Rate
The first force is the AI infrastructure boom. Global cloud providers’ capital expenditure on computing power exceeded $886.7 billion in 2026, and fiber has become the hardest physical bottleneck in the data center. Inside AI clusters, fiber is no longer just a telecom commodity—it is the physical layer connecting thousands of GPUs.
G.657.A2 fiber, with its bend-insensitive properties, is particularly suited for dense, high-density rack cabling in AI servers. According to the 2026 Global Fiber Optic Cable Industry Development Report, the spot price of G.657.A2 bare fiber in China rose from 83 RMB per core-kilometer in January 2026 to 216.91 RMB in June—a 161% increase in just five months. Overseas, the same fiber class trades at $21–25 per core-kilometer, two to three times the Chinese benchmark.
Fiber-Optic Drones Turn Fiber Into a Consumable
The second force is less obvious to traditional telecom buyers but equally disruptive. Fiber-optic FPV drones—the kind that deploy drone fiber optic spools for jam-resistant control and video transmission—consume kilometers of fiber per mission, and that fiber is not recovered. It is a one-way consumable.
Russia alone is projected to produce 4 to 5 million drones in 2026, each requiring several kilometers of fiber. This represents a entirely new demand category that did not exist at scale before 2024. Industry analysts now identify AI and drones as the “dual growth curves” driving fiber demand, together contributing 10%–20% of global marginal fiber demand.
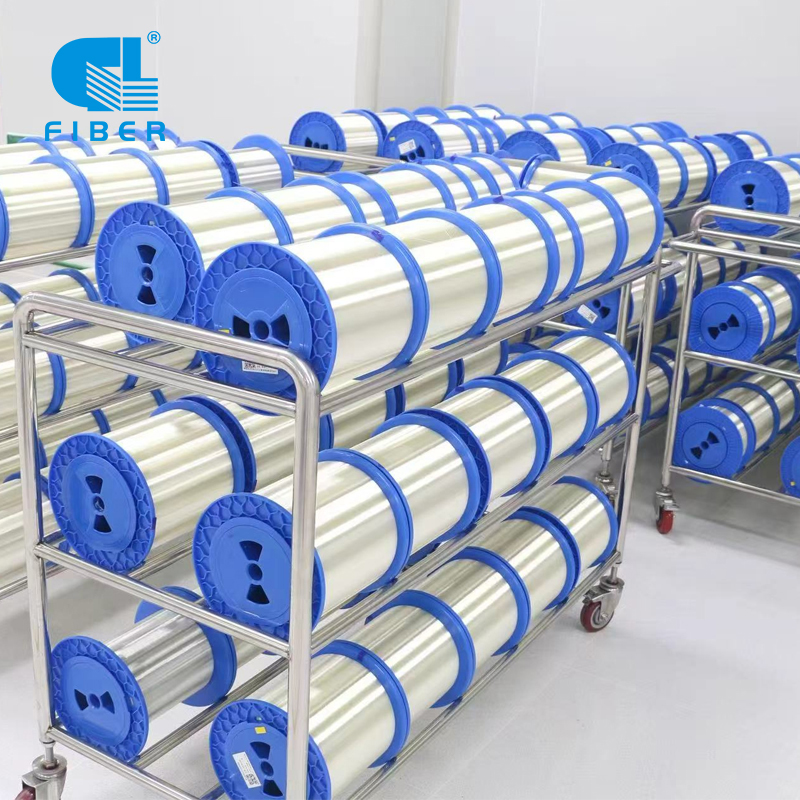
For suppliers of g657a2 bare fiber on 0.25mm/0.27mm spools—the exact format used in FPV drone reels—this demand spike has been overwhelming.
The Supply-Side Reality: Why Capacity Cannot Catch Up
Preform Expansion Takes 18 to 24 Months
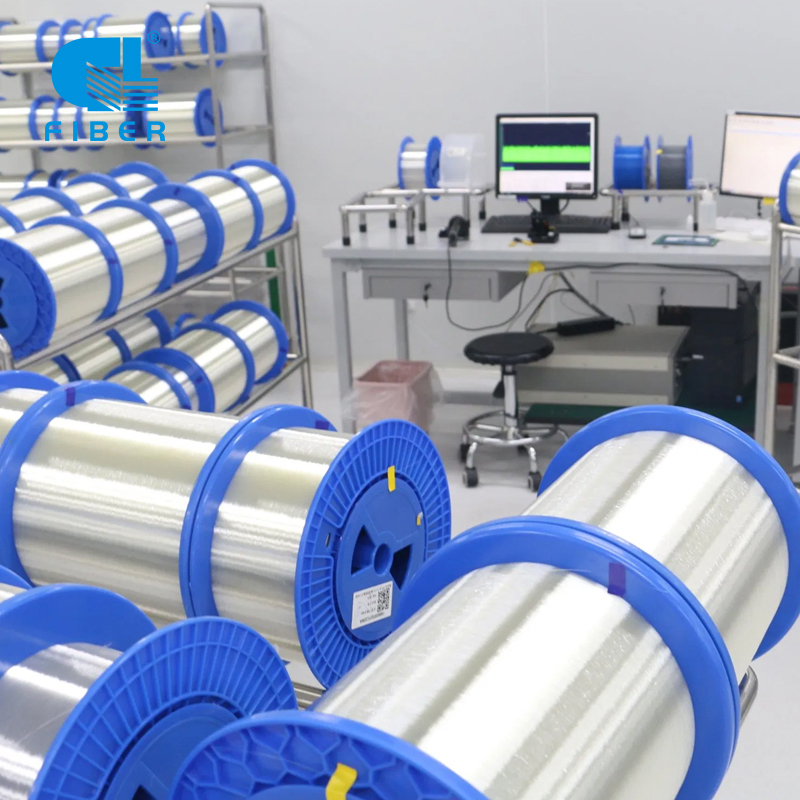
The critical bottleneck is not drawing fiber from preform; it is making the preform itself. A 3,500-ton preform facility requires approximately 4 billion RMB in investment and 18–24 months to build. Even if every major Chinese producer broke ground today, meaningful new capacity would not arrive until 2028 at the earliest.
In 2026, China’s effective preform capacity utilization rate reached 84.3%, while Corning’s North American plants exceeded 95%. There is simply no slack.
G657A2 Is Crowding Out Ordinary Fiber
Producers are reallocating preform capacity toward higher-value specialty fibers—G.657.A2 for drones and AI, G.654.E for long-haul data center interconnect—at the expense of standard G.652.D single-mode fiber. One manufacturer reported shifting 30%–40% of capacity to specialty fibers, yet still cannot meet orders, which grew fourfold year-on-year while actual shipments grew only twofold.
The math for 2026 is stark: global demand for G.657-class fiber is estimated at 370 million core-kilometers, while China’s effective capacity is only 200–210 million core-kilometers—a 46% shortfall.
Price Trends: What the Data Actually Shows
Buyers need to anchor expectations to verified numbers, not rumor. Here is what the market data confirms:
Fiber Type / Market Price Point Period Source
G.657.A2 (China spot) 83 RMB/core-km Jan 2026 2026 Industry Report
G.657.A2 (China spot) 216.91 RMB/core-km Jun 2026 Same report
G.657.A2 (overseas spot) $21–25/core-km 2026 Same report
G.657.A2 (annual comparison) 32 → 240 RMB/core-km (+650%) 2025 → 2026 CCTV Finance / multiple outlets
G.657.A2 forecast 220–250 RMB/core-km 2027 Industry forecast
Important nuance for SEO readers: The widely cited “650% increase” compares a low baseline in early 2025 to peak spot pricing in 2026. The more recent trajectory—from 83 RMB to 217 RMB in five months—better reflects the current pace. Forecasts suggest prices will hold in the 220–250 RMB range through 2027 before gradually easing after 2028.
For fpv fiber buyers purchasing in spool quantities (typically 0.25mm/0.27mm OD for drone applications), per-core-kilometer pricing translates to spool costs that must account for both fiber and precision winding. Do not expect bare fiber pricing to match standard telecom cable quotes.
Practical Sourcing Recommendations
1. Verify the Supplier’s Preform Position
In a shortage, the suppliers with the most reliable delivery are those with captive preform capacity or long-term preform supply agreements. Ask directly: “Do you produce your own preform, or buy from third parties?” A trader with no preform visibility cannot guarantee 2027 delivery, regardless of what the quotation says. Industry consensus is clear: “For most enterprises, locking in preform capacity is the most urgent task”.
2. Treat Price Validity as a Red Flag, Not a Convenience
If a supplier offers a 90-day price lock without a deposit, be skeptical. In the current market, legitimate producers are shortening quotation validity and requiring deposits to reserve capacity. A realistic arrangement is a deposit that secures a production slot, with final pricing adjusted against a published index (such as the industry report benchmarks) at shipment.
3. Match Fiber Specification to Application—Do Not Overpay for Unnecessary Performance
G.657.A2 is bend-insensitive and optimized for tight routing. For drone fiber optic applications, the key parameters are typically:
Cladding diameter: 125µm (standard)
Coating diameter: 0.25mm or 0.27mm (as specified in your product page)
Proof test level: Appropriate to reel tension during deployment
Attenuation: @1310nm and @1550nm within G.657.A2 standard
If your application does not require extreme bend performance, discuss G.657.A1 or standard sm fiber alternatives with your supplier. However, for FPV drone tether applications where the fiber must survive tight spooling and rapid deployment, G.657.A2 remains the correct choice.
4. Plan for Longer Lead Times and Consider Partial Shipments
Orders from major Chinese producers now extend into 2027. If your production schedule requires fiber in Q1 or Q2 2027, begin qualification now. Consider splitting orders across two qualified suppliers to reduce single-source risk, even if the second supplier commands a slight premium.
5. Distinguish Between “Cheap Fiber” and “Qualified Fiber”
The price surge has attracted traders offering fiber of uncertain origin. For drone applications, fiber failure during deployment means mission loss. Request:
Proof test certificates for each spool lot
Attenuation test data at operating wavelengths
Traceability to the drawing facility
A marginally lower price per spool is meaningless if the fiber breaks at kilometer 3 of a 10-kilometer mission.
Looking Ahead: When Will Relief Come?
Industry forecasts are consistent: the G.657.A2 supply tightness will not meaningfully ease before 2029. Preform expansion projects announced in 2026 will begin contributing capacity in 2028–2029, but demand from AI data centers and drone programs continues to grow. The fiber market has shifted from a telecom-cycle commodity to a strategic material, and pricing behavior reflects that new reality.
For buyers of g657a2 bare fiber, the practical takeaway is straightforward: qualify reliable suppliers now, accept that price volatility is structural rather than temporary, and build procurement plans around 2027 delivery realities rather than 2024 expectations.