The supply of G657A2 bare fiber is tightening again—and this time, the pressure is coming from a domestic Chinese tender that is quietly reshaping the global allocation landscape.
The 7.1 Billion RMB Tender That Changed Everything
In September 2026, China Mobile finalized its 2026-2027 ordinary optical cable procurement. The tender, valued at approximately 7.1 billion RMB, went through an unusual two-round process:
- The first round failed entirely—the price cap was set too low for manufacturers to participate
- After raising the maximum bid limit by 8.5%, the second round saw 17 of 18 bidders quote the absolute maximum price
- Final average: 102.56 RMB per core-km, a 90% increase over the previous round
What does this mean for G657A2 buyers? Manufacturers must dedicate preform and drawing capacity to fulfill this order. When China’s biggest carrier demands delivery, specialty fiber production gets pushed back.
The Real Bottleneck: Preform, Not Fiber
The root cause is upstream. Optical fiber preform accounts for approximately 70% of fiber manufacturing costs. Expanding preform capacity takes 18 to 24 months and requires massive capital investment.
According to CRU, China’s preform capacity utilization is already at 84.3%—effectively full load. There is no spare capacity to absorb a sudden spike in demand from any direction.
Why G657A2 Gets Squeezed First?
When preform is scarce, factories prioritize. And G657A2 sits at the bottom of the priority list for a specific reason: it is slower to produce.
Producing G657A2 requires more time per kilometer than standard G.652.D. For manufacturers under delivery pressure from carrier tenders, every hour of drawing capacity counts. This creates a structural disadvantage for specialty fiber—it consumes more production time for the same output.
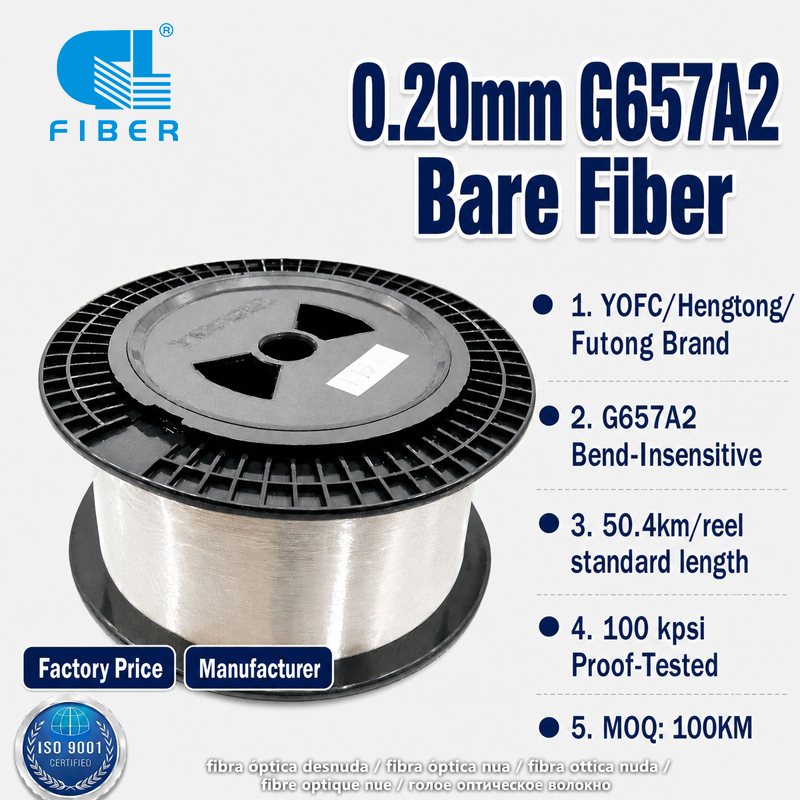
Meanwhile, demand for G657A2 has not slowed. The fiber is consumed in FPV drone applications and AI data center cabling, both of which continue to grow. Russia remains heavily dependent on Chinese imports, and international buyers are actively seeking 50.4km spools for drone programs.
What This Means for Buyers?
The supply tightness is real, but it is a matter of allocation priority, not disappearance. The practical implications:
Lead times are extending. Quotes are valid for shorter windows. 50.4km spools—which consume more fiber per unit—face tighter availability than shorter formats.
Price floors are firming. When manufacturers are committing capacity to carrier orders at 102.56 RMB/core-km for standard fiber, the opportunity cost of producing G657A2 at lower margins becomes harder to justify.
Direct factory relationships matter more than ever. In a constrained market, allocation follows relationships. Source factories prioritize clients with direct, long-term commitments over spot buyers and traders.
Conclusion
The G657A2 supply squeeze is not driven by a single factor but by the intersection of a massive domestic tender, preform capacity limits, and the structural disadvantage of specialty fiber production. For buyers, the takeaway is clear: secure supply early, verify your source factory, and plan for extended lead times.
GL FIBER is a source manufacturer of G657A2 bare fiber with full control over preform and drawing capacity. Contact us for current allocation and lead time information.